Thames Water has issued a stark warning to its creditors, confirming it requires an urgent £2.4 billion equity injection to prevent insolvency by early 2027. The utility provider, currently crippled by a massive debt pile exceeding £16 billion, faces a critical liquidity deadline as it attempts to finalize a wider refinancing deal amid intense regulatory scrutiny. This demand for emergency capital marks a pivotal moment for the UK’s largest water and wastewater supplier, bringing the possibility of a Special Administration Regime (SAR)—essentially a taxpayer-funded rescue—into sharper focus than ever before.
The Anatomy of the Liquidity Crisis
The £2.4 billion figure is not merely a request for operational breathing room; it is a fundamental requirement for the utility’s proposed turnaround plan. Thames Water, which serves approximately 16 million customers across London and the Thames Valley, has been operating under immense financial pressure following the withdrawal of support from its parent company, Kemble Water. The firm’s capital structure has been described by analysts as unsustainable, particularly given the escalating costs of necessary infrastructure maintenance and the urgent need to address systemic leakage issues.
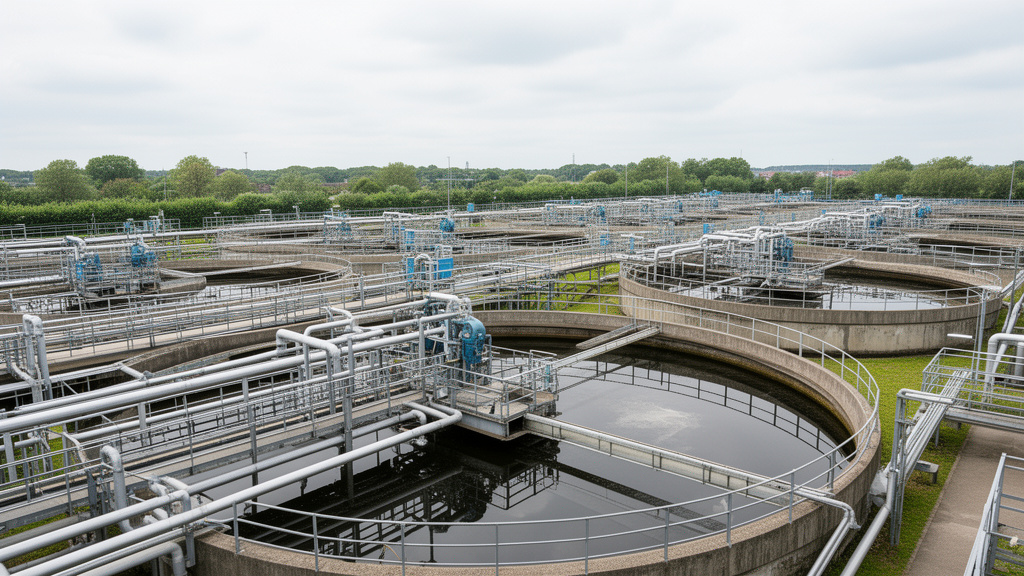
Without this immediate cash injection, the company faces a ‘liquidity cliff’—a point at which it will lack the cash reserves to meet its short-term debt obligations and operational expenditure. The management team has made it clear that while they are pursuing private equity solutions, the path to solvency remains narrow. The £2.4 billion is slated for ‘AMP8’ (Asset Management Period 8), the upcoming regulatory cycle in which Thames Water must invest heavily in infrastructure, wastewater treatment, and technology to meet stricter environmental targets set by the government and the regulator.
The Regulatory Standoff: Thames Water vs. Ofwat
Central to the company’s precarious position is its fraught relationship with the water regulator, Ofwat. The tension stems from a disagreement over allowable returns and the level of investment required to repair the crumbling network. Ofwat has consistently challenged the company’s business plans, arguing that they do not go far enough in protecting consumer interests or addressing the root causes of service failures.
Thames Water, conversely, has argued that Ofwat’s proposed revenue caps make it impossible to attract the necessary investment to turn the business around. This stalemate has created a feedback loop of negativity: the regulator’s skepticism discourages potential investors, while the lack of investment ensures the company continues to underperform, further damaging its reputation and financial outlook. The £2.4 billion request is therefore an attempt to bridge this divide, proving to both the regulator and the markets that the company is serious about its reform agenda, regardless of the challenging regulatory backdrop.
Infrastructure, Debt, and the 2027 Deadline
Beyond the boardroom, the crisis has tangible, real-world implications. Thames Water is currently managing a network that has seen decades of under-investment. With a debt-to-equity ratio that has historically been high, the rising interest rate environment has made servicing this debt significantly more expensive.
If the company fails to secure the £2.4 billion, it may be forced into the Special Administration Regime. Under this mechanism, the government would take control of the water provider to ensure the continuity of service—a process that would effectively wipe out current shareholders and impose significant costs on the taxpayer. The date of early 2027 is significant because that is when the utility estimates it will effectively run out of ‘headroom’ in its financial covenants and liquidity buffers.
Beyond the Numbers: The Future of UK Utility Models
The crisis at Thames Water is prompting a national conversation about the efficacy of the private utility model in the UK. Many critics argue that the privatization of water has prioritized dividend payouts and shareholder returns over the long-term integrity of the infrastructure. The struggle to raise £2.4 billion highlights the difficulty of reconciling public utility mandates with private capital requirements. If the company cannot find a way to make itself ‘investable,’ the government may have no choice but to consider more radical restructuring options, potentially including a move toward a mutual or public-interest ownership model. As the deadline approaches, all eyes are on the company’s board and its ability to secure a deal that avoids the ultimate failure of Britain’s largest water utility.